Money Lessons Fathers Should Teach Before Children Leave Home
What Every Father Should Teach His Children About Money Before They Leave Home
I learned some of my most important money lessons after the damage had already been done.
Bankruptcy taught me that earning money is not the same as knowing how to manage it. A person can work hard, bring home a paycheck and still be one emergency, one bad loan or one careless decision away from financial trouble.
That is not a lesson I want my children to learn only through pain.
Before they leave my home, I want them to understand more than how to make money. I want them to know how to keep some of it, plan with it, protect it, recover from mistakes and use it to build a stable life.
Fathers do not need to be wealthy or financially perfect to teach these lessons. We need to be honest about what we know, what we learned late and what we are still improving.
Our children should not have to pay full price for lessons we have already paid for with our mistakes.
The short answer: What should fathers teach children about money?
Before children leave home, fathers should teach them how to earn money, create a realistic budget, spend less than they receive, build emergency savings, use bank accounts, understand paychecks and taxes, borrow carefully, build credit, recognize scams, begin investing for long-term goals and make financial decisions based on values rather than appearances.
The goal is not to turn every child into a financial expert. The goal is to make sure ordinary adult money decisions do not feel completely unfamiliar when no parent is standing beside them.
Why money lessons must begin before adulthood
Money will touch nearly every part of your child’s adult life: housing, transportation, education, work, relationships, health, emergencies and future opportunities.
Yet knowing financial terms is not the same as having financial habits.
The Consumer Financial Protection Bureau’s Money as You Grow program emphasizes that children develop money skills, habits and attitudes over time. Fathers can help by involving children in age-appropriate decisions and explaining real choices involving earning, saving, spending and sharing.
The need is real. According to the Federal Reserve’s 2025 household survey, only 63 percent of adults said they could cover a hypothetical $400 emergency using cash or its equivalent. Only 55 percent had savings for three months of expenses, and among adults ages 18 to 29, that figure was 37 percent.
Those numbers are not reasons to frighten children. They are reasons to prepare them.
1. Teach them that money is earned by creating value
Children often see money appear without seeing the work, skill, patience or sacrifice behind it.
They see a card tapped at a register. They see a package arrive. They may not see the hours worked, taxes withheld, bills paid or decisions made before the purchase.
Teach your children that money is generally earned by solving problems, creating value, developing skills and keeping commitments.
This does not mean paying children for every basic household responsibility. Some work is done because they are members of the family. But age-appropriate opportunities to earn can teach the connection between effort, reliability and compensation.
Try this at home
Give your child a paid project beyond normal chores. Agree on the expected result, deadline and payment before the work begins. Afterward, discuss whether the work was completed well and what made it valuable.
The lesson is bigger than the amount earned: your reputation and your ability to solve problems affect your opportunities.
2. Teach them to tell every dollar where to go
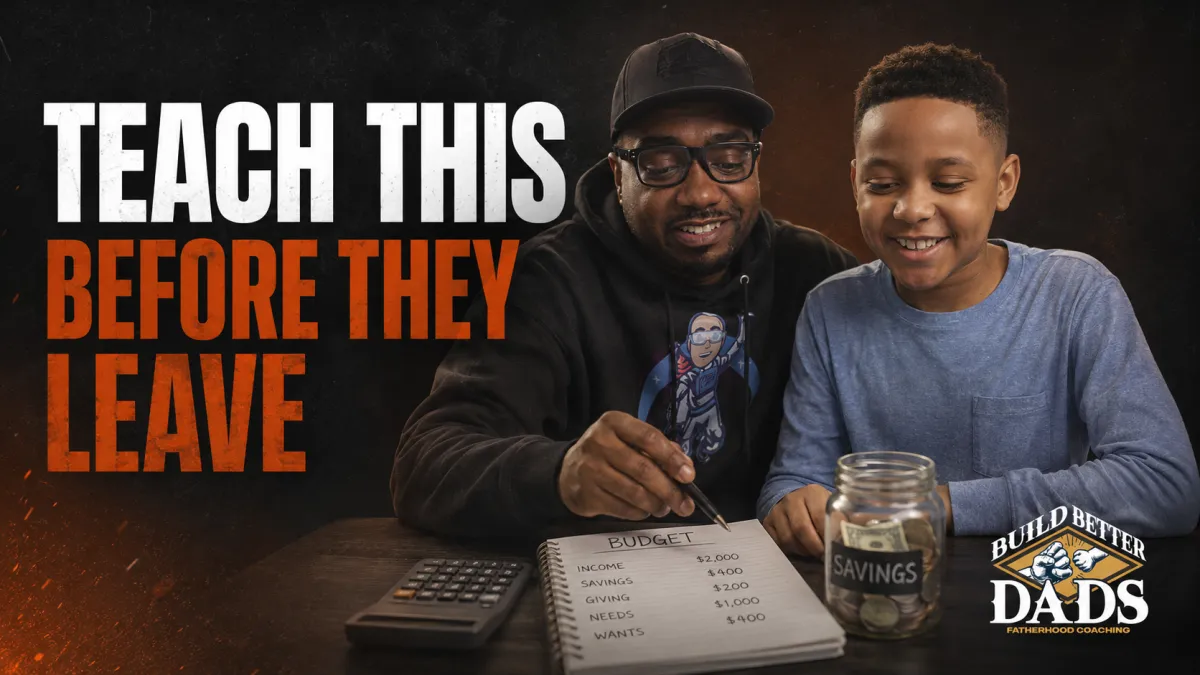
A budget is not a punishment. It is a plan made before emotions, advertisements and pressure make the decisions.
Teach your child to divide income into simple categories:
Giving or sharing
Saving
Essentials
Future goals
Enjoyment
The exact percentages may change with age, income and responsibilities. The habit that matters is deciding before spending.
Children should also understand the difference between:
A need and a want
A recurring expense and a one-time purchase
A price and the total cost of ownership
Having enough money to buy something and being able to afford it responsibly
A car, for example, is not only a purchase price or monthly payment. It may also require fuel, insurance, registration, repairs and maintenance.
Try this at home
Give your child a realistic monthly amount and a sample list of expenses. Let them build the budget. Do not immediately correct every choice. Ask what they would change if the income dropped or an unexpected expense appeared.
3. Teach them to save before life forces them to borrow
Emergencies do not ask whether it is a convenient month.
A tire fails. Work hours are reduced. A phone breaks. A medical bill arrives. Without savings, an ordinary problem can become expensive debt.
Teach your children to “pay themselves first” by moving part of their income into savings before spending the rest.
Start with a goal they can understand:
Save a small starter emergency fund.
Build enough to cover a realistic unexpected expense.
As income and responsibilities grow, work toward several months of essential expenses.
The first emergency fund does not need to be impressive. It needs to exist.
This is why I believe in helping young people build a small financial war chest. The amount may begin with $50, $100 or $500 depending on their age and income. What matters is learning that savings create breathing room and choices.
Try this at home
Help your child choose one savings goal, name it and track progress visually. When the goal is reached, discuss what made it possible before choosing the next target.
4. Teach them how bank accounts and paychecks actually work
Before leaving home, a young person should know how to:
Open and manage a checking and savings account
Read an account balance and transaction history
Use a debit card without treating the balance as unlimited
Set alerts for low balances and unusual transactions
Avoid overdraft and unnecessary fees
Deposit income and transfer money between accounts
Protect passwords, cards and personal information
Read a pay stub
A paycheck is also not the same as take-home pay.
Children entering the workforce should understand that gross pay may be reduced by taxes, Social Security, Medicare, insurance, retirement contributions or other deductions. They should know why keeping pay stubs, tax forms and basic financial records matters.
Try this at home
Review a sample pay stub together. Ask your child to identify gross pay, deductions and net pay. Then build a budget using the net amount—not the larger number at the top.
5. Teach them that credit is borrowed trust
Credit can help an adult rent a home, finance an appropriate purchase or qualify for better terms. It can also make yesterday’s purchase expensive for months or years.
Before your child uses credit, explain:
The difference between a debit card and a credit card
Interest and annual percentage rate
Minimum payments
Late fees
Credit limits and utilization
How payment history can affect a credit profile
The total cost of borrowing
Why cosigning creates responsibility for another person’s debt
Teach them never to focus only on whether they can make the monthly payment. They must ask how much the purchase will cost in total and what else that payment will prevent them from doing.
Debt is not merely a math decision. It is a claim on future income.
Try this at home
Use a simple loan or credit-card calculator. Compare the original price with the total paid under different interest rates and payment amounts. Let the numbers make the lesson visible.
6. Teach them to protect themselves from scams and financial pressure
Young adults are not only learning how money works. They are also being targeted by people who understand their urgency, trust and desire to belong.
Teach your children to slow down when someone:
Promises guaranteed returns
Pressures them to act immediately
Requests passwords, verification codes or sensitive information
Demands payment by gift card, cryptocurrency or wire transfer
Offers a job that requires them to send money first
Asks them to move money for someone else
Uses romance, fear, embarrassment or authority to stop them from asking questions
They should also understand identity theft, account alerts, secure passwords, credit-report monitoring and why suspicious messages should be verified through an official channel.
The Federal Reserve reported that 20 percent of adults experienced financial fraud or scams in 2025. Protection is therefore not an advanced lesson. It is part of basic financial readiness.
Try this at home
Show your teenager a few sample scam messages. Ask them to identify the warning signs and explain how they would verify whether the request is legitimate.
7. Teach them that investing is patient ownership—not fast money
Saving protects near-term goals. Investing can help build wealth for goals that are years or decades away.
Children should understand the basic ideas before they encounter online promises of overnight success:
Compound growth rewards time and consistency
Higher potential returns generally involve higher risk
Diversification helps avoid depending on one investment
Fees reduce returns
An emergency fund should not depend on volatile investments
Money needed soon should be treated differently from long-term money
Speculation is not the same as a financial plan
You do not need to recommend a specific stock or investment product. Teach the principles, show how time matters and encourage your child to learn from qualified, trustworthy sources before risking money.
Try this at home
Use a compound-growth calculator to compare starting small at a young age with waiting ten years to begin. Focus on the lesson of time, consistency and patience—not a guaranteed result.
8. Teach them that money decisions reveal priorities
Money is not the purpose of life, but it affects the life a person can build.
Teach your children to ask:
What am I trying to build?
Does this purchase support that goal or compete with it?
Am I buying this because I value it or because I want approval?
What responsibility comes with this decision?
Am I leaving room to help others?
Financial success should not be measured only by what someone owns. A person may display expensive things while carrying debt, stress and no margin for emergencies.
Teach children to value stability over appearance, options over applause and generosity without self-destruction.
Try this at home
Share one financial choice you regret and one choice that helped your family. Explain the result without pretending you always knew the right answer.
Let children practice while the consequences are still small
Lectures are not enough.
Children need controlled opportunities to earn, plan, choose, spend, save and make mistakes while the consequences are still manageable.
A child who spends all their discretionary money and has to wait may learn more than a child whose parent immediately replaces it.
A teenager who helps compare phone plans may understand recurring costs better than one who is simply told that bills are expensive.
A young adult who creates their own moving budget will be better prepared than one whose parent handles every detail.
The goal is not to let children fail dangerously. It is to stop removing every small consequence that could teach them how decisions work.
What if you are still rebuilding your own finances?
Teach from the rebuilding.
You can say:
“I did not learn this early enough. Here is the decision I made, what it cost me and what I do differently now.”
That kind of honesty gives your child something more valuable than the appearance of perfection.
If you are budgeting for the first time, let them see part of the process. If you are paying down debt, explain the principle without placing adult anxiety on the child. If you are building an emergency fund, celebrate progress instead of hiding the fact that you had to begin.
Your financial mistakes do not disqualify you from teaching. Refusing to learn from them would.
A money-readiness checklist before your child leaves home
Before your son or daughter moves out, see whether they can:
Explain how they earn and receive income
Build a monthly budget using take-home pay
Track spending and read account activity
Distinguish needs, wants and financial goals
Maintain checking and savings accounts
Build and protect an emergency fund
Read a pay stub and recognize common deductions
Explain interest, credit and the total cost of debt
Compare financial options instead of choosing only by monthly payment
Identify common scams and protect personal information
Explain the difference between saving and investing
Plan for rent, utilities, food, transportation and insurance
Ask for help before a financial mistake becomes a crisis
Do not use this list only as a test. Use it to identify the next lesson your family should practice together.
Frequently asked questions
At what age should fathers start teaching children about money?
Start as soon as a child notices that money is exchanged for things. Young children can practice choosing, waiting and saving toward a goal. Older children can earn money, compare prices and make simple budgets. Teenagers can learn banking, paychecks, taxes, credit, fraud protection and the real cost of living.
Should children receive an allowance?
An allowance can help children practice planning and delayed gratification, but families use different approaches. Make clear which responsibilities are expected because the child belongs to the household and which additional projects may earn money. The learning matters more than copying another family’s exact system.
Should parents tell children about their financial mistakes?
Yes, in an age-appropriate way. Share the lesson, the consequence and what you changed without making the child responsible for adult financial stress. Honest stories can make abstract warnings real.
What money skills should a teenager know before getting a first job?
A teenager should understand gross and net pay, common paycheck deductions, basic tax forms, direct deposit, budgeting, saving, account security and workplace expectations. They should know that the hourly wage multiplied by hours worked will not necessarily equal the amount deposited.
How much should a child save from each paycheck?
There is no percentage that fits every situation. Help the child choose a consistent amount based on income, necessary expenses and goals. Saving before discretionary spending is more important than pretending one fixed percentage works for everyone.
Should a young adult build savings or pay off debt first?
Many people need to do both: build a small emergency buffer while making required debt payments, then direct additional money according to interest costs, risk and personal circumstances. For individualized financial advice, consult a qualified professional who can review the complete situation.
Should parents give adult children money when they struggle?
Help should solve or stabilize a real problem without automatically removing responsibility. Clarify whether the money is a gift or loan, what must change and whether the help supports a larger independence plan.
How can fathers teach money when they do not earn much?
Money lessons are not reserved for wealthy families. Children can learn planning, comparison, saving, avoiding scams, caring for possessions, developing skills and making thoughtful choices at any income level.
Begin with one lesson this week
Do not wait until the night before your child moves out and try to explain an entire financial life.
Choose one lesson and make it practical.
Open a savings account. Review a pay stub. Build a sample budget. Compare the total cost of a car. Show what interest does. Talk about a mistake. Set a savings goal.
The conversation does not have to be perfect. It has to begin early enough for your child to practice.
Money will teach them eventually.
Our job as fathers is to make sure life is not their first teacher.
For the broader conversations every boy needs before adulthood, read 7 Conversations Every Father Should Have With His Son Before He Turns 18.
If your adult child already lives at home, read Should Your Adult Child Pay Rent to Live at Home? A Father’s Guide to Building Independence.
You can also download The UnBreakable Son Ebook and subscribe to the Build Better Dads YouTube channel for practical lessons about financial resilience, relationships, character and fatherhood.